Insured From the Kerb: Getting Cover Right Before You Collect a Used Car
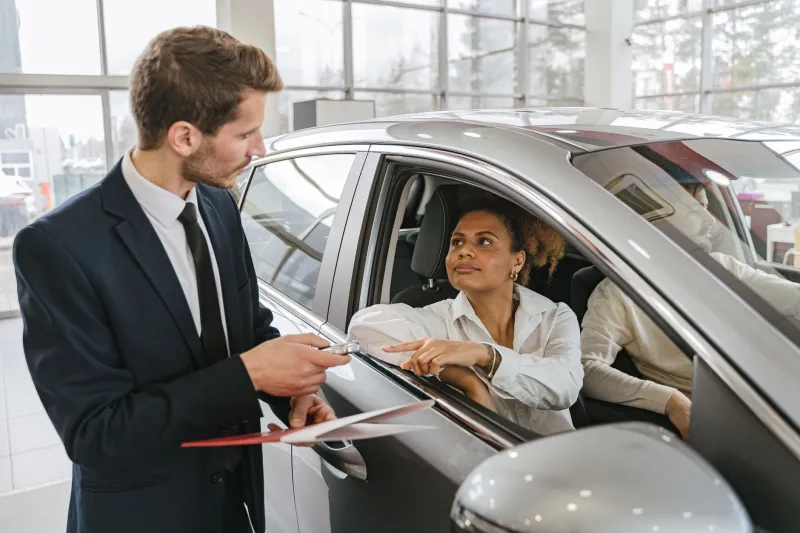
You've agreed the price, paid the balance and been handed a coffee. The car is sitting outside with your name on the V5C/2. Then someone says: 'You're insured to drive it home, yeah?' And you realise you have absolutely no idea.
That moment — between the forecourt and your front door — is where a surprising number of otherwise sensible purchases turn into a problem. The law is straightforward: under section 143 of the Road Traffic Act 1988, you must have at least third-party insurance in place to drive on a public road. Your mate's policy, the dealer's trade plates or a hopeful phone call to your insurer on Monday morning won't cut it if you're stopped on the A-road home.
Here's how to close that gap properly, without paying over the odds or assuming cover you don't have.
The dealer's insurance is not your insurance
It's worth saying plainly, because it comes up every week: a dealer's motor trade policy covers the business and its employees. It may cover you on a test drive, but it does not cover you to drive your new purchase home as a private buyer. Trade plates are for the trade, not a handy free pass for customers. If anyone tells you to 'just stick the plates on and go', walk away from that conversation and sort your own cover.
Some dealers do offer driveaway insurance — often a short-term policy arranged through a partner insurer, commonly seven days. That can be genuinely useful. But it isn't universal, it isn't free, and it comes with conditions around age, licence type, claims history and the vehicle itself. Ask exactly what it covers, what the excess is, and what happens on day eight. If it's not offered, don't assume it can be arranged at the last minute.
Replacing your old car? Read your existing policy first
If you're part-exchanging or selling your current car and buying a replacement, many comprehensive policies include a short grace period — often seven or fourteen days — during which the new car is covered on the same terms. That sounds like the answer to everything, but the details matter.
Usually you must already be a policyholder, the old car must have been sold, written off or otherwise disposed of, and you need to tell your insurer that the switch has happened. Some policies cover the replacement comprehensively; others drop to third-party-only cover until you formally update the policy. The grace period often ends the moment you sell the old car, not when you buy the new one. And if you're keeping the old car as well, this isn't a replacement at all — it's a second vehicle, and a different conversation entirely.
Before collection, ring your insurer and ask three questions: is the new car covered from the moment I drive it away, at what level of cover, and can you email me confirmation? A note on your file is good; something in writing is better.
The 'any car' clause is not a golden ticket
Plenty of drivers believe their comprehensive policy lets them drive any car third-party. Sometimes it does — but the driving-other-cars extension is narrower than the folklore suggests. It usually provides third-party cover only, often excludes vehicles owned by you or hired to you, and may not apply if the other car isn't insured elsewhere. Some policies exclude it for drivers under a certain age or in certain occupations.
Crucially, it is not a substitute for insuring a car you've just bought and now own. If the V5C is being transferred into your name, the car is yours. Relying on a DOC extension to drive it home is exactly the sort of assumption that looks clever until it doesn't.
Adding a second car is a different job
If you're buying a used car to sit alongside the one you already run, replacement cover won't help. You need a separate policy, a multi-car arrangement, or short-term temporary insurance. Temporary cover can be arranged online in minutes, but check the excess, the mileage limit, whether the vehicle is eligible and what happens if you need to extend it. It can be pricey for younger drivers or high-value cars, and it isn't available for every modified or imported vehicle.
Your no-claims discount can normally only be used on one car at a time. Some insurers will mirror or match it on a second policy; many won't. Ask before you assume.
The pre-collection checklist
Before you leave home to collect the car, have these sorted:
- The registration number and exact model — insurers need both, and trim levels matter.
- A confirmed start time — not just a date. If you're collecting at 6pm, the cover needs to start before then.
- Written confirmation — a certificate, an email or a policy schedule. Screenshots beat vague memories.
- Tax arranged — you can't tax a car without insurance in place. The dealer may be able to do it online with the new keeper supplement, but confirm who is doing what.
- MOT checked — if the car needs one, it needs to be valid before you drive it away.
- A phone signal and a charger — boring, but useful when you're standing in a car park trying to activate a policy.
The Motor Insurance Database can lag behind a new policy by a day or more, so carry your certificate or confirmation email with you. If you're stopped, it's far easier to show proof than to explain that your insurer probably knows.
If the deal falls through
Temporary policies and new policies usually have a cooling-off period, but admin fees can eat into any refund. Don't cancel your old policy until the new one is live, and don't let a dealer pressure you into driving away before cover is confirmed. A five-minute delay in the handover is nothing compared with a fine, a seized car or an uninsured claim.
At Hyde Motors, we'd rather you asked the awkward insurance question before you pay than discovered the answer halfway home. The gap between the forecourt and your front door is small — but it's the most expensive place to be uninsured.